In West Virginia, even downtown Charleston is a rural Opportunity Zone. Starting January 1, 2027, that label decides whether 30% or 10% of a deferred gain goes untaxed after five years. Here is what the statute requires of a rural fund, how Treasury drew the line on its final list, and what the difference is worth on a $500,000 gain.
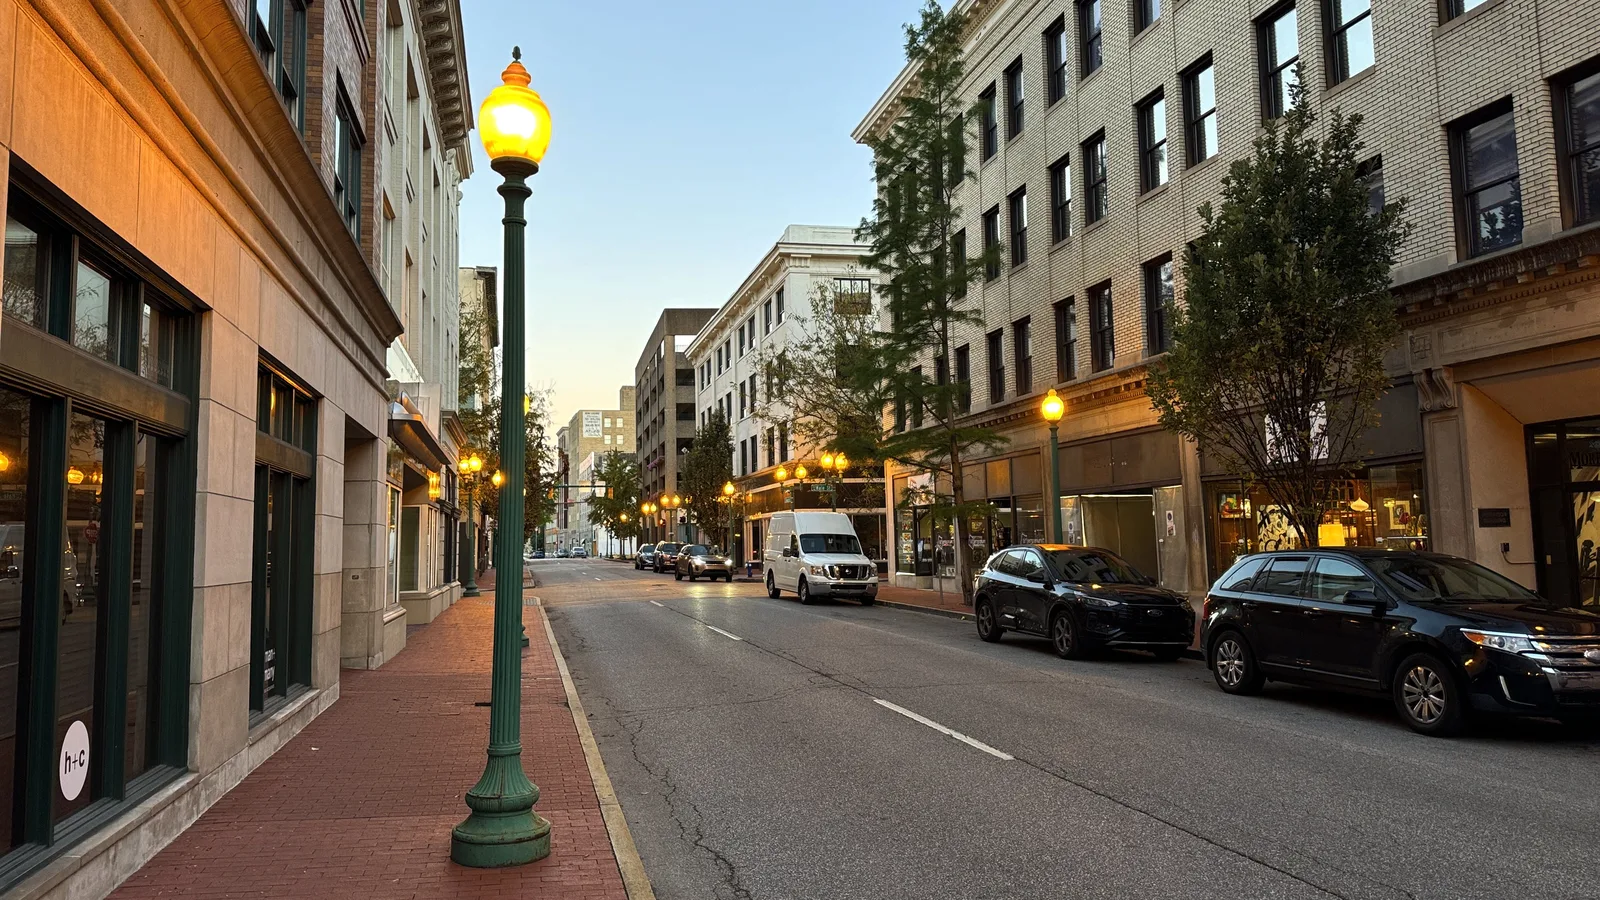
CHARLESTON, W.Va. — Quarrier Street runs through downtown Charleston, the capital of West Virginia, past brick office blocks, storefronts and old-fashioned lampposts. It does not look like farm country. On Treasury’s final list of Opportunity Zones for 2027, though, the census tract around it is rural.
Lead photo: Quarrier Street in downtown Charleston, West Virginia, in 2024. Downtown lies in census tract 9 of Kanawha County, which is on Treasury’s 2027 final list as a rural Opportunity Zone. Credit: GrmnB / Wikimedia Commons, CC BY-SA 4.0; cropped and resized.
That isn’t an error. It is how the law now defines “rural,” and starting January 1, 2027, the label carries real money. An investor who puts a capital gain into a fund that keeps its money in zones like this one can have 30% of the deferred gain go untaxed after five years. In a standard fund, the figure is 10%.
The difference rests on two things: one sentence of statute and one column in a Treasury spreadsheet.
Two funds, one law
The 2025 budget law, Public Law 119-21, rewrote Section 1400Z-2 of the tax code for money invested in qualified opportunity funds after December 31, 2026. Under the new rules, an investor who sells an asset at a gain and puts that amount into a fund within 180 days can defer the tax. The deferral ends at the earlier of a sale or “the date which is 5 years after the date the investment in the qualified opportunity fund was made.”
Five years is also when the reward arrives. Under the amended statute, an investment held that long gets a basis increase “equal to 10 percent (30 percent in the case of any investment in a qualified rural opportunity fund) of the amount of gain deferred.” The statute treats that increase as occurring before the tax comes due, so it reduces the bill in the same year.
Two other features apply to both kinds of fund. The old 5% bonus for a seven-year hold does not appear in the new rules. And an investor who holds for at least 10 years can elect a basis equal to fair market value when the investment is sold. That election wipes out tax on the investment’s appreciation, now with a limit: for investments still held at 30 years, fair market value is measured on the 30th anniversary. IRS Notice 2026-55 restates the 10% and 30% figures.
What makes a fund “rural”
The statute does not let a fund call itself rural. A qualified rural opportunity fund is one that “holds at least 90 percent of its assets” in opportunity zone property whose use is in a zone “comprised entirely of a rural area.” The property can be a building or equipment used there, or stock or a partnership interest in a business whose tangible property is used there. The 90% is measured the way the ordinary fund test is: an average of two dates each tax year.
That test sits on top of the 90% asset test every qualified opportunity fund already has to meet. If more than a tenth of a fund’s assets sit anywhere else, including in a non-rural zone, it falls short.
“Rural area” has its own definition in the same section. It means “any area other than— (I) a city or town that has a population of greater than 50,000 inhabitants, and (II) any urbanized area contiguous and adjacent to a city or town described in subclause (I).” The IRS noted in Notice 2025-50 that the wording matches the definition the Agriculture Department uses for its rural development programs.
How Treasury drew the line
Treasury’s Office of Tax Analysis explained how it turned that sentence into a map in a March 2026 methodology. It began with every incorporated city and town over 50,000 people in the 2020 Census, using Census-designated places for Hawaii and Puerto Rico. It added each Census urban area that “touches or overlaps the area of such a city or town at least at one point.” A tract counts as rural only if it doesn’t overlap any of that territory, apart from a small allowance for slivers caused by boundary mapping.
Treasury’s example is Frederick, Maryland, which had more than 78,000 residents in 2020. The main part of the Frederick urban area counts against nearby tracts. Detached “islands” of the same urban area don’t, so a tract that touches only an island can still be rural.
Charleston’s case is simpler. The 2020 Census counted 48,864 people in Charleston and 46,842 in Huntington. No place in the state topped 50,000, and all 52 of West Virginia’s designated tracts are flagged rural, including tract 9 in Kanawha County, which covers Quarrier and Capitol streets downtown. In Treasury’s eligibility file, tract 9 has a poverty rate of 51.7% and a median family income of $30,640, about 39.5% of the area median. Vermont looks the same: its largest city, Burlington, had 44,743 residents in 2020, and all 24 of its designated tracts are rural.
What the final list shows
Treasury’s final list, published with press release sb0682 on November 5, designates 6,576 tracts. Of those, 2,594 are rural. The designations workbook marks each one in a column called “Rural QOZ.” That column reads “Rural” when the zone “is comprised entirely of a rural area,” the statute’s own words. Each zone’s ID also starts with an “R” or an “N.”
The shares vary widely. Rural tracts make up 39.4% of the list nationally, 17.1% of California’s 620 tracts and one of Rhode Island’s 25. None of the District of Columbia’s 25 is rural. The county isn’t a reliable guide either: 116 counties have both rural and non-rural zones on the list. The only reliable check is the individual tract, on our map, in the designation checker or on the rural and urban breakdown.
The arithmetic on $500,000
Take an investor who realizes a $500,000 long-term capital gain and puts all of it into a qualified opportunity fund in early 2027. The starting basis is zero. Assume the investment is still worth at least $500,000 at the five-year mark, since the statute taxes the lesser of the deferred gain or the investment’s fair market value at that date.
| At year five | Standard fund | Rural fund |
|---|---|---|
| Gain deferred | $500,000 | $500,000 |
| Basis step-up | 10% × $500,000 = $50,000 | 30% × $500,000 = $150,000 |
| Deferred gain taxed | $500,000 − $50,000 = $450,000 | $500,000 − $150,000 = $350,000 |
| Federal tax at a hypothetical 20% rate | $90,000 | $70,000 |
The 20% figure is for illustration only. It is the top federal long-term capital gains rate in IRS Topic 409. The rate that applies in 2032 will depend on the investor’s income and the law then, and the 3.8% net investment income tax and state taxes can apply as well. Our October explainer ran the same gain at a combined 23.8% rate.
After year five, the two paths come back together. Once the tax is paid, each investor’s basis rises by the gain that was taxed, and both end up at $500,000. From then on, the 10-year election works the same way for both. The rural advantage is a one-time difference in the amount of deferred gain that is taxed: $100,000 in this example.
A lower bar for renovation
Rural zones also get a building rule that is already in force. A fund that buys an existing building generally has to “substantially improve” it, adding more than the property’s adjusted basis over 30 months. For property in a zone comprised entirely of a rural area, the statute cuts that to 50%. Unlike the step-up, the change took effect when the law was signed on July 4, 2025. Notice 2025-50 applied it to 3,309 rural zones on the 2018 map, and the same statutory text covers rural zones on the 2027 list. Our substantial improvement calculator runs both thresholds.
What isn’t settled yet
The statute says the 90% rural test is measured like the ordinary fund test. It doesn’t say what happens to an investor’s 30% step-up if a fund falls below that line partway through a five-year hold. Treasury and the IRS said in Notice 2026-40 that they plan to propose regulations. Notice 2026-55 asks for public comments, due November 23, 2026, on whether more guidance is needed.
What happens next
Until those rules arrive, the steps before January 1 are practical ones. Confirm that each tract is on the final list and flagged rural. Read how a fund describes measuring its rural assets. And work through the five-year date with a tax adviser, since that is the year the deferred gain is taxed.
Investors funding either kind of QOF from a property sale still face the same recognition clock: how the 180-day clock works for sellers. A 1031 exchange cannot use a fund interest as replacement property (can you 1031 into an Opportunity Zone?); sellers weighing a Delaware statutory trust against a QOF should read DST vs Opportunity Zone fund.
Related. Rural 30% step-up: what Notice 2026-55 says, and what it is worth on a $500K gain · Rural bonus guide · OZ 2.0 guide · The 10-year rule · Qualified opportunity funds · West Virginia Opportunity Zones · Kanawha County Opportunity Zones · 2,594 rural Opportunity Zones designated for 2027 · Basis step-up and 10-year exclusion calculator
Reporting note: Tract 9’s poverty rate and median family income were read from Treasury’s October 30, 2026 eligibility file. Rural and non-rural counts, shares and the R/N zone IDs were counted from Treasury’s final-list designations workbook. City populations are 2020 Census redistricting-file totals. Statute quotations are from 26 U.S.C. § 1400Z-2 as amended by Public Law 119-21, checked against IRS Notices 2025-50, 2026-40 and 2026-55. Educational reporting, not tax, legal or investment advice.
Not tax advice.
FAQ
What is the difference between a rural and a standard qualified opportunity fund?
For amounts invested after December 31, 2026, both defer a reinvested capital gain for up to five years. At five years, a standard fund’s investors get a basis step-up of 10% of the deferred gain. In a qualified rural opportunity fund, which must hold at least 90% of its assets in property used in zones comprised entirely of a rural area, the step-up is 30% (IRC §1400Z-2(b)(2), as amended by Public Law 119-21).
What counts as a rural area for Opportunity Zones?
The statute defines a rural area as any area other than a city or town with more than 50,000 inhabitants and any urbanized area contiguous and adjacent to such a city or town. Treasury applies this with 2020 Census places and urban areas, and a zone qualifies only if it is comprised entirely of a rural area.
How can I tell whether a 2027 Opportunity Zone is rural?
Treasury’s designations workbook for the final list has a Rural QOZ column, and each zone ID begins with R for rural or N for non-rural. Of the 6,576 designated tracts, 2,594 are rural. You can look up a tract on Opportunity Zone Invest’s map or in the designation checker.
How much is the rural step-up worth on a $500,000 gain?
At five years, assuming the investment is worth at least $500,000, a standard fund taxes $450,000 of the deferred gain and a rural fund taxes $350,000. At a hypothetical 20% federal rate, that is $90,000 versus $70,000. Actual rates depend on the investor and the law in effect at the time. Not tax advice.
- law.cornell.edu, as of November 18, 2026
- govinfo.gov, as of November 18, 2026
- irs.gov (1), as of November 18, 2026
- irs.gov (2), as of November 18, 2026
- irs.gov (3), as of November 18, 2026
- irs.gov (4), as of November 18, 2026
- home.treasury.gov (1), as of November 18, 2026
- home.treasury.gov (2), as of November 18, 2026
- home.treasury.gov (3), as of November 18, 2026
- home.treasury.gov (4), as of November 18, 2026
- www2.census.gov (1), as of November 18, 2026
- www2.census.gov (2), as of November 18, 2026
- irs.gov (5), as of November 18, 2026
- irs.gov (6), as of November 18, 2026
Original reporting by the Opportunity Zone Invest Editorial Team for Opportunity Zone Invest, an independent OZ 2.0 research site. Facts are drawn from the primary sources cited above per our editorial standards. Nothing here is tax, legal, or investment advice. Found an error? See our corrections policy or write to Opportunity Zone Invest.
OZ tools: Opportunity Zone calculator · OZ 2.0 designation checker · 180-day rule calculator · Form 8997 instructions · Form 8996 instructions · all tools
Get OZ 2.0 updates
OZ 2.0 news, guidance, and key deadlines. Unsubscribe anytime.